I. Introduction
Europe is one of the world’s most demanding markets for China construction machinery. Stage V emissions, CE certification, CBAM carbon tariffs, and anti-dumping investigations create formidable barriers, while Volvo, Liebherr, JCB, Caterpillar, and Komatsu have long dominated. Yet Chinese manufacturers are steadily expanding.
Based on January–September 2026 value-based data, this article examines the market share landscape, competitive segments, and country patterns of China’s top 10 OEMs, with practical references for buyers. Figures are industry estimates covering new machines only. “Europe” refers to the EU plus Western, Southern, and Northern Europe, excluding Russia and CIS. Data tolerance is ±11–14%.
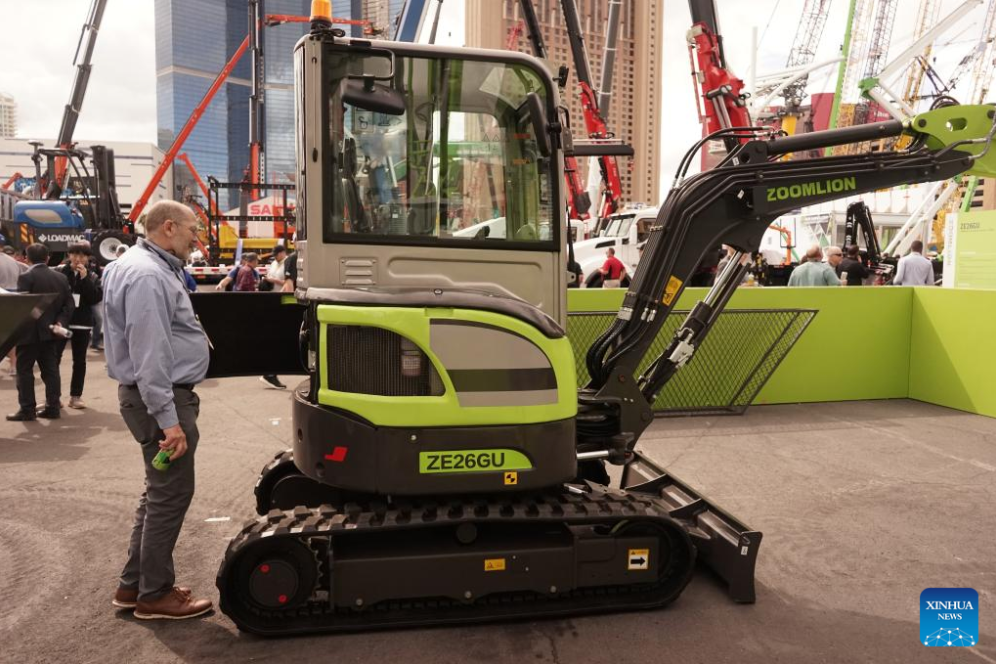
II. The European Construction Equipment Market: Where Chinese Brands Stand
The total europe construction equipment market (FOB import value) reached approximately USD 4.7–5.4 billion in the first three quarters of 2026.
Non-Chinese brands hold 84–88%, maintaining absolute dominance.
Chinese brands account for 12–16% of the total construction equipment market by value, with FOB exports of roughly USD 560–860 million.
Smaller Chinese manufacturers, mainly mini excavators, represent 3–5% of Chinese brand exports.
Buyer Takeaway: Chinese brands now hold over one-tenth of the European market. Spare parts, after-sales service, and technical support networks are maturing. For budget-conscious buyers with delivery timeline requirements, leading Chinese brands now qualify for the shortlist.
III. Top 10 China Construction Equipment Manufacturers: Ranking and Tiers
Within the Chinese cohort, share is highly concentrated. The top 10 china construction equipment manufacturers account for 95–97% of Chinese brand exports to Europe, while CR3 (Sany, XCMG, Zoomlion) holds 77–89%.
Tier 1: Sany, XCMG, Zoomlion
1. Sany leads with 34–38% of Chinese-brand internal share. Core strengths: excavators (including electric), concrete machinery, cranes. Its Putzmeister acquisition provides a deep European foundation. Key markets: Germany, France, Spain, Nordics. Total European import share: 4.1–6.1%.
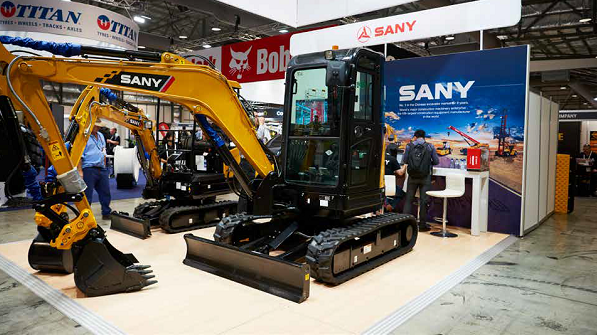
2. XCMG follows with 27–31%: full-range excavators (including electric), cranes, compaction. It operates a Düsseldorf training center and a European rental division. Key markets: Germany, Netherlands, Poland, Italy. Total European import share: 3.2–5.0%.
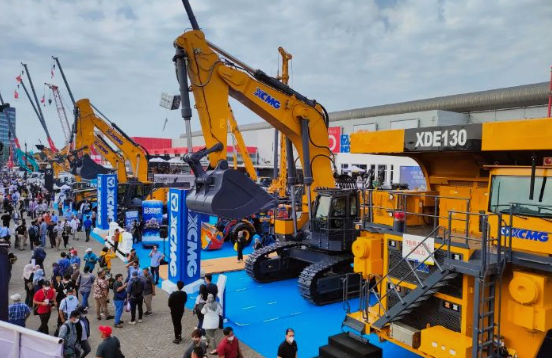
3. Zoomlion holds 16–20%: tower cranes, aerial work platforms, concrete machinery. It has a German factory and a Hungarian aerial platform plant. Key markets: Germany, Austria, Hungary, Czech Republic. Total European import share: 1.9–3.2%.
Tier 2: LiuGong, SDLG, Sunward
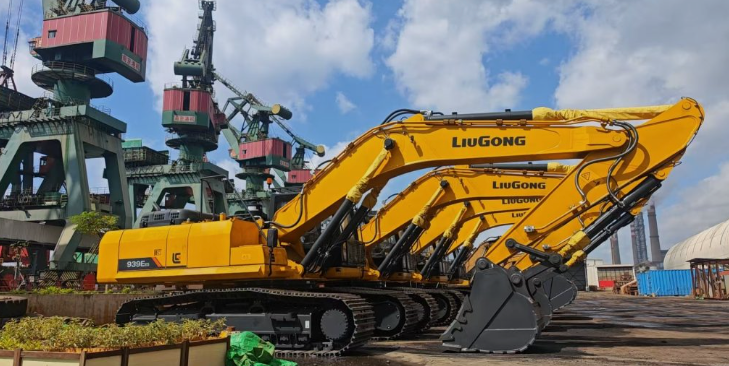
1. LiuGong holds 7–9.5%: small and medium excavators, loaders. Its Polish factory is central to its European strategy. Key markets: Poland, France, Spain.
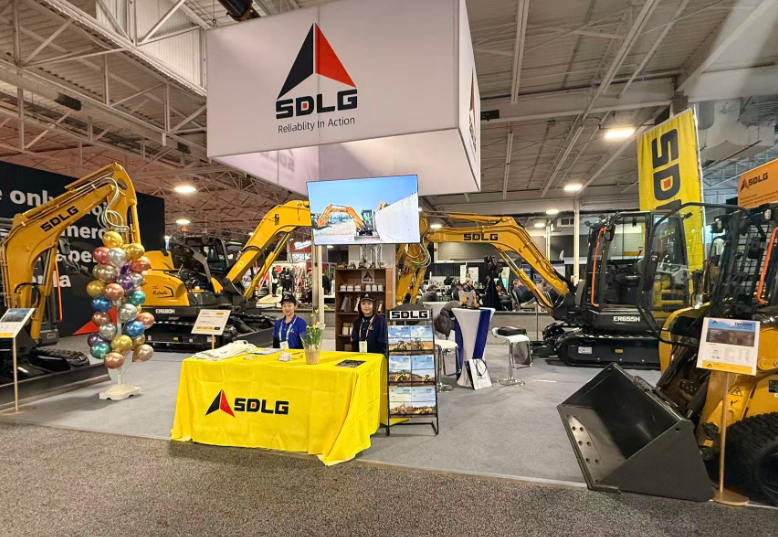
2. SDLG holds 4–6%: small excavators and loaders, leveraging Volvo channel synergy, focused on Southern and Eastern Europe.
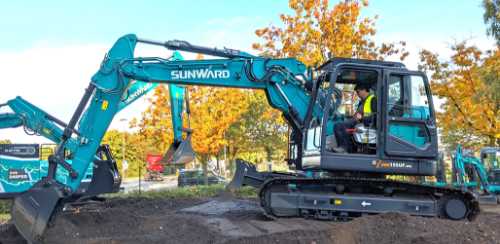
3. Sunward holds 2.2–3.5%: mini and small excavators, small-tonnage rotary drilling rigs. Key markets: Italy, Spain, Eastern Europe.
Tier 3: Shantui, Lonking, XGMA, Lovol
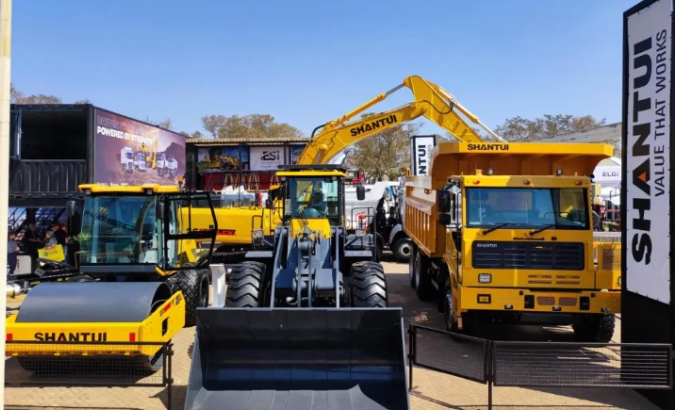
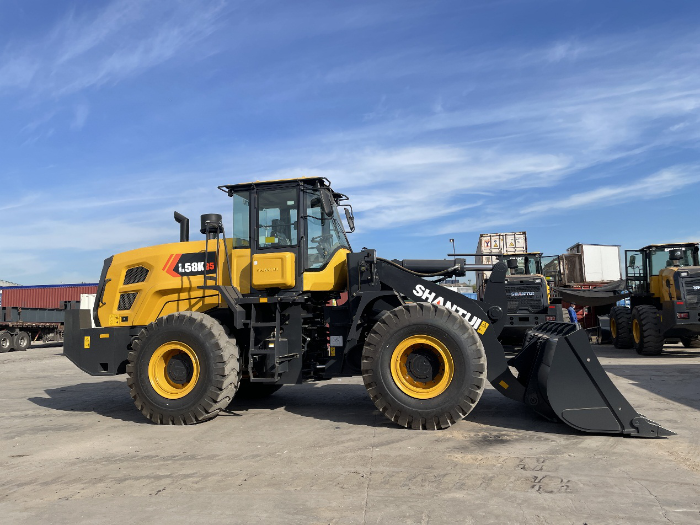
Shantui holds 1.0–2.0%: bulldozers and rollers, mainly project-based orders in Eastern Europe.
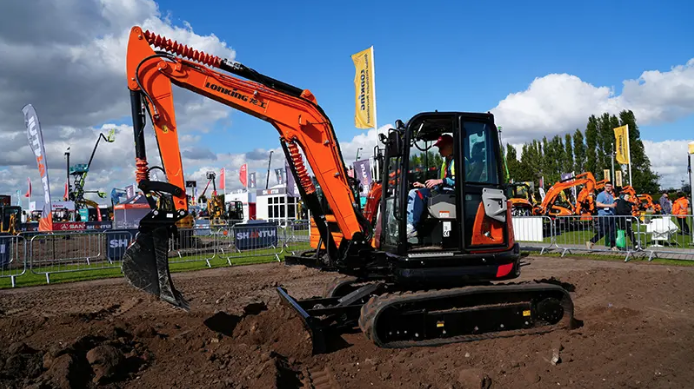
Lonking holds 0.6–1.2%: economy small earthmoving equipment via trade channels.
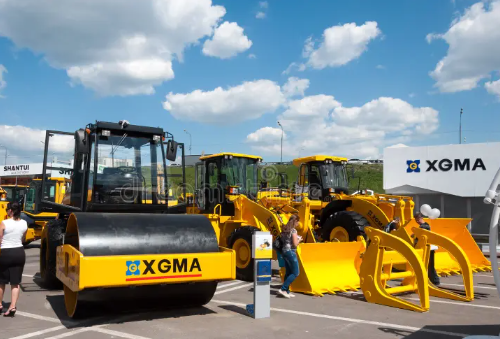
XGMA holds 0.2–0.7%: sporadic mini excavator trade orders, no complete European-compliant product line.
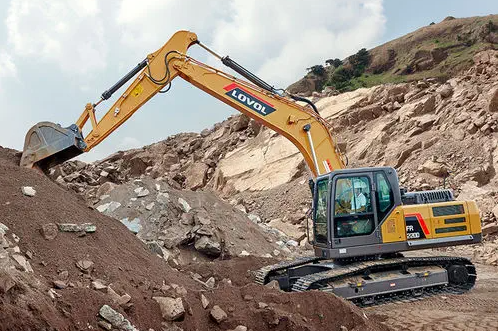
Lovol holds 0.1–0.5%: minimal exports, incomplete compliance setup.
Buyer Takeaway: Tier 1 players have the largest localization investments, offering more reliable parts networks and secondary market liquidity. Tier 2 offers competitive options in specific regions and categories. Tier 3 suits price-sensitive buyers with in-house service capabilities.
IV. Product Segments: Where Chinese Brands Win
Mini and small excavators are the easiest entry point. European rental companies purchase in volume and are price-sensitive. Sany, XCMG, and Sunward lead.
Medium and large excavators remain dominated by non-Chinese brands. Sany and XCMG have limited breakthroughs with electric models, but diesel-powered units in this class are unlikely to challenge incumbents short-term.
Concrete machinery is led by Sany (Putzmeister synergy) and Zoomlion. High-end Western Europe remains dominated by Putzmeister and Schwing; Chinese brands gain volume in cost-competitive Eastern Europe.
Piling machinery is small overall. Bauer and Liebherr hold absolute dominance; Sany and XCMG have limited shipments.
Aerial work platforms are the fastest-growing category for Chinese brands. Zoomlion’s Hungarian factory enables local manufacturing, but the segment faces anti-dumping pressure.
Bulldozers and loaders see LiuGong, SDLG, and Shantui as main participants, concentrated in Central and Eastern Europe.
VI. Outlook 2026–2030
Electrification is the core breakthrough. Electric excavators, loaders, and aerial platforms are where Chinese brands have competitive product strength. Traditional diesel medium-to-large equipment will struggle short-term. For China construction machinery suppliers, this is the single most important lever for share gains.
Regional divergence will continue. Central and Eastern Europe will gain faster; Western Europe slowly. Anti-dumping, CBAM, and evolving regulations create uncertainty across the construction equipment market.
Head concentration will increase. CR3 will continue to dominate. LiuGong stabilizes Tier 2 via its Polish factory; SDLG and Sunward focus on small equipment; Lonking, XGMA, and Lovol will struggle to scale given compliance investment requirements.
Local manufacturing is replacing direct exports. Factories in Germany, Poland, and Hungary reduce tariffs and logistics costs while improving spare parts response.
Risk constraints remain significant. EU investigations, carbon taxes, and safety/emission regulations will cap Chinese brand share. By 2030, total market share is unlikely to exceed 22%.
Buyer Takeaway: For long-term holds, prioritize brands with local European factories or subsidiaries. For short-term resale, factor in currently lower residual values.
Buyer Takeaway: For mini excavators, electric equipment, or aerial platforms, Chinese brands offer sufficient choice with clear cost-performance advantages. For medium-to-large diesel equipment or piling machinery, non-Chinese brands remain safer, with Chinese brands suitable as supplements or pilots.
V. Country-Level Patterns
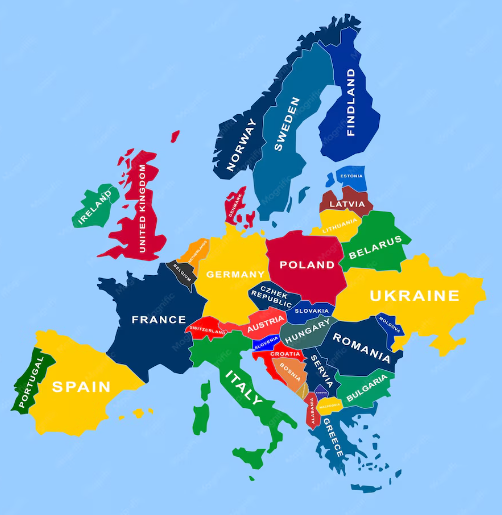
Germany, Europe’s largest market, is dominated by Liebherr, Volvo, and JCB. Among Chinese brands, Sany leads, primarily via mini excavators and electric equipment.
Central and Eastern Europe (Poland, Hungary, Czech Republic) has lower barriers. XCMG and Sany are roughly equal, with LiuGong close behind.
Southern Europe (Spain, Italy) has strong small equipment demand. Sany, Sunward, and XCMG lead.
Western Europe (France, Netherlands, Nordics) has the highest barriers, with strict service and spare parts requirements. Sany and XCMG are main players, but share growth is difficult. Across the europe construction equipment landscape, regional divergence remains the defining feature.
Buyer Takeaway: In Central and Eastern Europe, Chinese brands’ local service is approaching non-Chinese levels, making procurement risk relatively low. In Western Europe, carefully evaluate dealer service capability and spare parts inventory, and specify after-sales response times in contracts.
VII. What This Means for Buyers
Supply stability: Leading china construction equipment manufacturers now have local factories or subsidiaries—Sany in Germany, Zoomlion in Germany and Hungary, LiuGong in Poland—with spare parts and after-sales approaching non-Chinese levels. This significantly reduces supply disruption risk compared to exporters relying solely on whole-machine shipments.
Compliance risk: Stage V and CE are the baseline, but anti-dumping and CBAM are variables. Specify compliance responsibility and tariff-bearing clauses in contracts.
Residual values: Chinese brands currently have lower residual values than Volvo or JCB, but leading brands’ small and electric equipment is improving. Factor this into short-hold cost calculations.
Service network: Central and Eastern Europe service is approaching non-Chinese levels; Western Europe varies. Visit dealers in person to assess capability and spare parts depth before purchasing.
VIII. Conclusion
China construction equipment manufacturers’ performance in Europe during January–September 2026 presents a clear picture: concentrated at the top, tiered in structure, segmented by product category, and gradient by region. Sany, XCMG, and Zoomlion together hold nearly 80–90% of Chinese-brand internal share, forming the undisputed Tier 1. LiuGong, SDLG, and Sunward constitute Tier 2, each with distinct focus areas. Shantui, Lonking, XGMA, and Lovol remain marginal due to compliance and channel limitations.
By segment, mini and small excavators and electric equipment are where Chinese brands are most competitive. By region, Central and Eastern Europe offer lower barriers and faster penetration, while Western Europe requires long-term cultivation. By business model, local manufacturing is replacing direct exports as the necessary path for leading brands to establish a European foothold.
For European buyers, the key question is not whether to consider Chinese brands, but which tier and product category aligns with your risk tolerance and service requirements. Electrification and localization will be the core variables determining whether Chinese brands can secure a lasting position in Europe’s high-end market over the next five years—and the key signposts for buyers to watch.
In the field of compaction and earthmoving equipment, QHMACH offers a complete product line covering road rollers, excavators, and loaders. Our road rollers span ten tonnage segments from 12 to 36 tons, excavators cover 1 to 30 tons, and loaders cover 3 to 17.5 tons. All products are Stage V and CE certified, meeting European market access requirements. If you are evaluating Chinese-brand compaction or earthmoving equipment, visit Qhmach to learn more about product specifications and certifications.